 ordinex
OrdinexData — Financial Intelligence API
Point-in-time financial data
for systematic traders.
Build and backtest strategies on SEC filings, insider activity, institutional flows, and financial factors - using only information that was actually available at the time. One REST API, built to feed trading systems and research pipelines directly.
Why this matters
Backtest the past without knowing the future
Point-in-time · Restatement-safe · No look-ahead
Company reports
A 10-K, 10-Q, or 8-K is filed with the SEC.
Filing goes public
The filing's own filed_date is stored alongside the data.
Nothing is overwritten
Restatements arrive as new rows - the original reported value stays intact.
Query with as_of
Every endpoint filters by filed_date <= as_of.
Backtests can't cheat
A historical query only ever sees what was actually knowable on that date.
Signal library
Everything your strategy needs, already computed
A sample of what's live today - the full endpoint-by-endpoint reference is further down this page.
Quality
ROIC · Profitability · Piotroski F-Score · Sloan Accruals
Ownership
Insider buying/selling · Insider consistency · Institutional flow · Ownership concentration
Valuation beta
P/E · P/B · P/S
Events
8-K classification · Filing-delay trends · Amended-filing tracking
Macro & rates
CPI · GDP · Treasury yields · Real rates · Credit spreads - direct from FRED
See which of these are empirically validated, and which aren't →
Example workflow
Build a point-in-time value strategy
Select a universe
Screen tracked US companies by sector, size, or any factor threshold.
Go back in time
Query fundamentals and factors as_of a historical date, e.g. 2019-01-01.
Score the universe
Rank by value and quality percentiles as they stood on that date.
Hold the top decile
Take the highest-ranked names as that period's equal-weighted portfolio.
Roll forward
Repeat the screen at the next rebalance date, month by month.
Or skip the loop
GET /backtest runs this exact process for you, end to end.
Every step above queries only data that was actually knowable on that historical date - no look-ahead bias, by construction.
Why OrdinexData
Built for systematic research, not another dashboard
Build vs. buy
Why not just pull SEC EDGAR and FRED yourself?
Both sources are free and public. Plenty of teams do pull them directly - here's what that actually takes, beyond the download.
Validation
We test our factors. We don't assume they work.
Most financial data vendors hand you a list of computed metrics and let you assume they're predictive. We go a step further: every derived factor runs through walk-forward backtesting and regime-stability tests against real market data before it earns a "validated" label - and some don't pass. That's intentional, not a bug.
"Cleared" means a factor passed our walk-forward backtesting gates against real market data - it does not mean proven, stable alpha. One of the nine (open-market insider purchases) is a "core factor" (Tier 1); the other eight are regime-dependent components (Tier 2), not standalone core signals. Six of the nine show a positive relationship with forward returns; three show a negative one. Four match the direction their own motivating academic literature predicted (insider purchases, earnings yield, R&D intensity, earnings stability) - the rest run counter to naive intuition or to their own literature, disclosed plainly rather than glossed over. The most recent addition, a real (inflation-adjusted) interest-rate factor, is also our first result from a genuinely new hypothesis class: macro/regime signals, not just company-level fundamentals. Full methodology and results, including every tested candidate that didn't clear the bar, are public in our GitHub repository.
Full breakdown of every signal we've tested, including what didn't pass →
Architecture
How data becomes a signal
Connectors
SEC EDGAR and FRED, direct public-domain sources. Market data supplements the SEC-only factors while in beta.
Storage
Append-only, point-in-time - queries reconstruct what was known as of any date.
Scheduler
Refreshes on an interval, computes factor scores forward.
REST API
Filters, screens, ranks, backtests - all over HTTP.
Alerts & dashboard
Pull-based event conditions, and a thin read-only client over the same API.
What's included
Every endpoint below is live, not on a roadmap
SEC- and FRED-sourced data below is public-domain and available now. Rows marked (beta) are sourced from an unofficial third-party feed for evaluation only - not licensed for redistribution or commercial use - and will be offered under a licensed data provider once one is contracted. Self-service signup keys are scoped to the non-beta rows only; see Terms.
Full breakdown of every data source, real tracked concepts, and filing type →
Pricing
Free during the private beta - pricing not final
Early access to the public-domain endpoints is genuinely free, not a bait-and-switch trial - the tiers below are the honest direction pricing is headed, not a live checkout.
Early Access
- SEC/FRED-sourced (public-domain) endpoints
- Point-in-time factor scores
- Standard rate limit
Pro
- Higher rate limits
- Commercial usage rights (public-domain endpoints)
- Priority support
Enterprise
- Custom rate limits
- Dedicated data requirements
- Commercial licensing
- Research / data partnerships
Quickstart
From zero to your first factor score
Get an API key
Sign up below for a free self-service key, scoped to the public-domain (SEC/FRED) endpoints - just an email address, no credit card. Keys with beta-market-data access are still issued manually (see Access below).
Call an endpoint
Send it as the X-API-Key header on every request.
Read the response
Every factor for that date, in one object - missing factors are null, not a reason to drop the row.
Reference
Full endpoint reference, generated from the API itself
Every request/response shape below is generated straight from the running API, so it never drifts out of sync with what's actually deployed.
Dashboard
API-first. Dashboard when you need it.
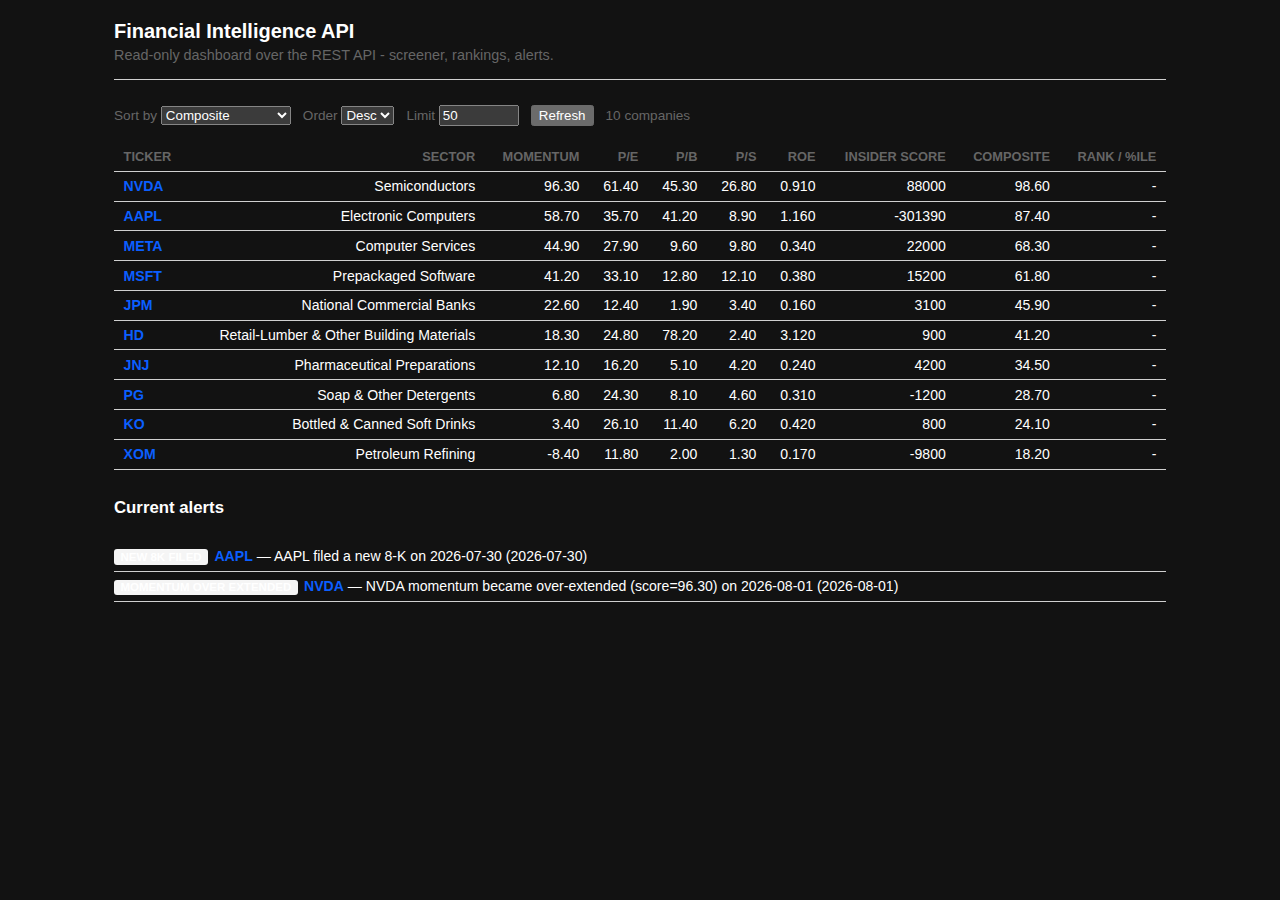
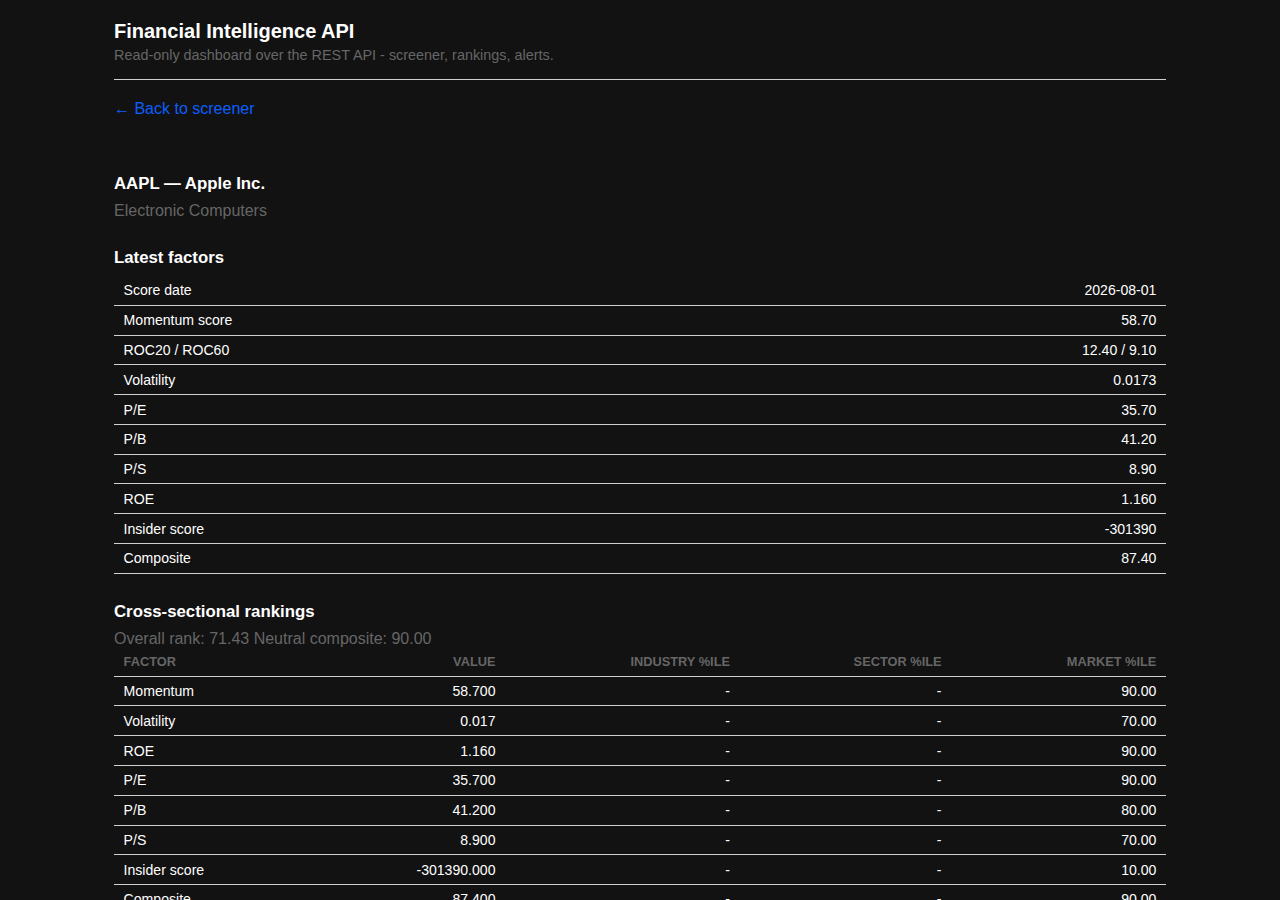
The product is the API above - GET /dashboard is a thin, read-only client over those same endpoints, useful for a quick look, not the main interface.
Access
Build your next strategy on data you can trust
Free during the private beta - one active key per email. Keys may be revoked without notice while this project is pre-launch. Self-service keys are scoped to the SEC/FRED-sourced (public-domain) endpoints listed above only - beta-tagged, Yahoo-sourced market-data endpoints are not licensed for redistribution or commercial use and will be offered once a suitable licensed data provider is contracted.
Prefer to talk first, need a higher limit, or want a beta-scoped key for evaluation in the meantime?